The Global Close: October 26, 2026 — AI optimism returns as Anthropic files and oil retreats
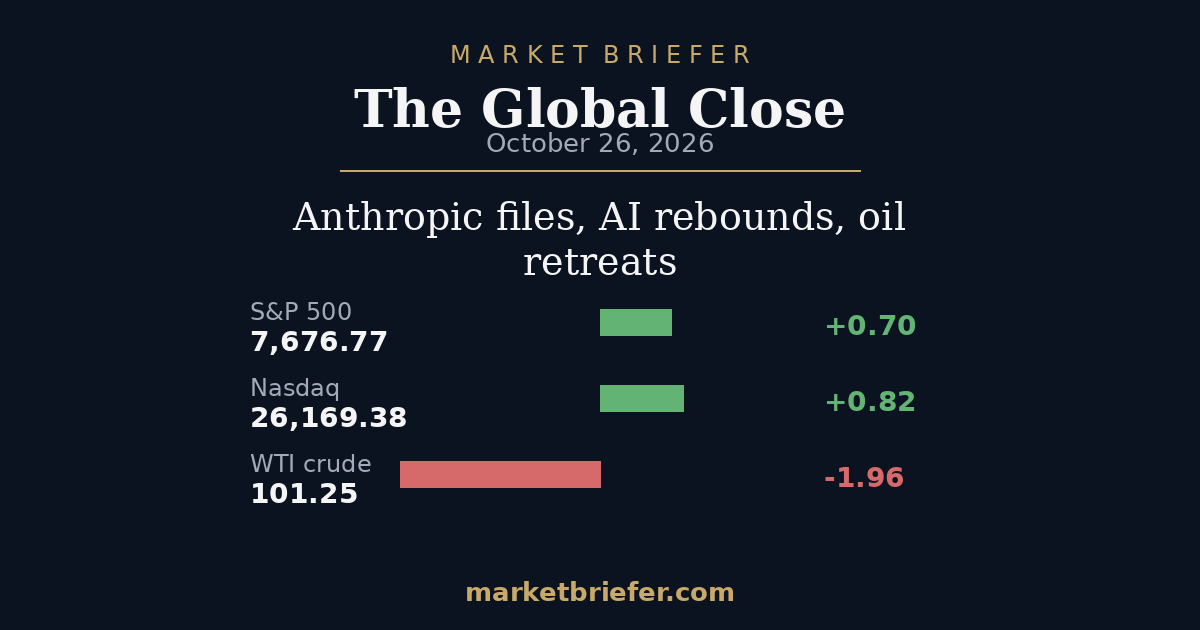
The S&P 500 rose 0.7% to 7,676.77 and the Nasdaq gained 0.8% as Anthropic's IPO filing revived AI shares, Europe rose across the board, Brazil crashed after Lula's surprise win, and Brent crude fell back from Friday's spike.
8 min read
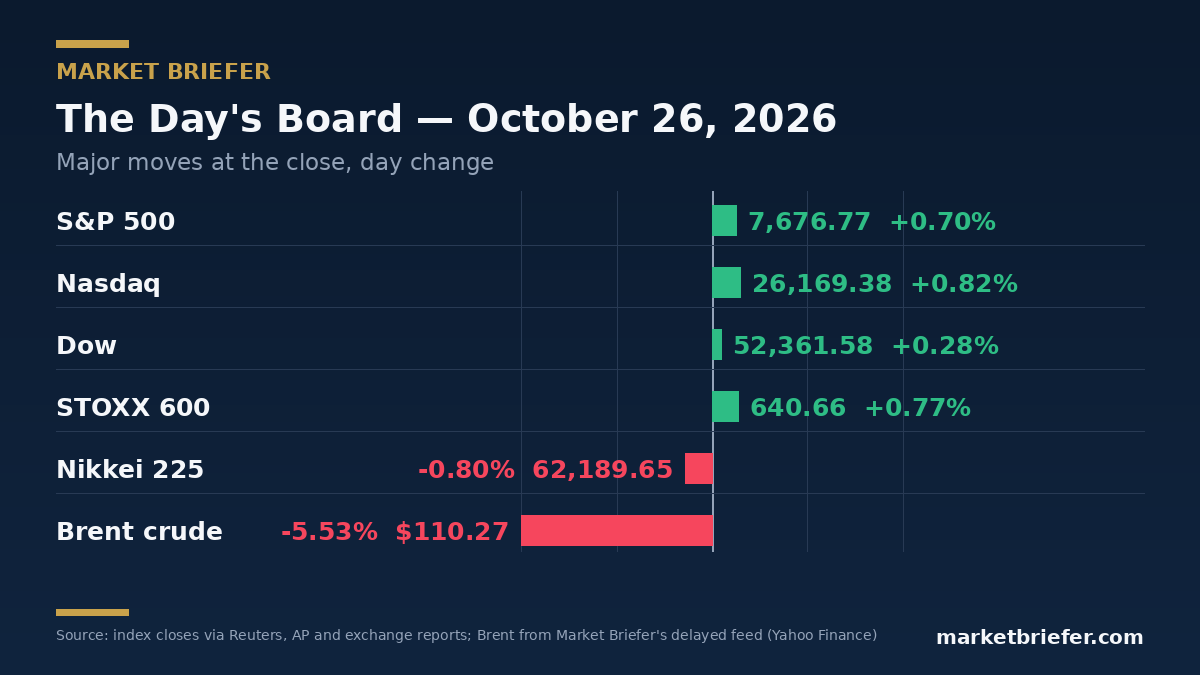
Wall Street opened the week higher, and for once this month the reason was the technology trade itself. The S&P 500 rose 53.09 points, or 0.70%, to 7,676.77, the Nasdaq Composite gained 214.04 points, or 0.82%, to 26,169.38, and the Dow Jones Industrial Average added 146.42 points, or 0.28%, to 52,361.58, after Anthropic made its U.S. IPO filing public and investors gave the artificial intelligence build-out the benefit of the doubt, Reuters reported. Europe rose across the board, with the STOXX 600 up 0.77% to 640.66, while oil gave back much of Friday’s war premium as Saudi, Pakistani and Turkish officials headed to Tehran for talks and Brent crude fell in Market Briefer’s delayed data to $110.27 a barrel. The exception was Brazil, where the Ibovespa plunged about 13.7% after Luiz Inácio Lula da Silva’s surprise runoff victory wrong-footed investors who had positioned for his opponent. With the 10-year Treasury yield holding just below 5%, at 4.98%, the session read as a positioning day ahead of the week’s real tests: the Federal Reserve decision on Wednesday, Microsoft and Alphabet earnings the same evening, and Thursday’s growth and inflation data. Those with most at stake are borrowers and homebuyers, whose costs track the 10-year yield, and AI shareholders, whose employers are raising capital at a pace that will be judged company by company this week.
The Number That Matters: $95 billion — the size of Meta Platforms’ planned equity raise. Meta said it intends to raise up to $95 billion in its largest-ever equity fundraising — about $35 billion of stock offerings launched, plus an at-the-market programme of up to $60 billion — Reuters reported, to fund AI infrastructure as its capital spending reaches a guided $135 billion to $145 billion this year. The figure matters more than the Nasdaq’s 0.82% gain because it is the transmission point between the month’s two fighting forces: at a 10-year yield near 5%, debt-funded AI spending is what investors punished last week, so the build-out is increasingly financed with equity instead, diluting holders — Meta’s shares fell 1.88% — while chipmakers Nvidia, AMD and Broadcom indicated interest in buying up to $5 billion of the new stock. Strong Microsoft and Alphabet earnings on Wednesday would make their cash generation, not Meta’s fundraising, the more important signal.
United States
The rebound was led by the shares that fell hardest last week. The Philadelphia semiconductor index rose about 3%, Reuters reported, though it remains down nearly 12% for October, and the Nasdaq 100 added 1.09% to 29,273.40 in Market Briefer’s delayed data. Technology was the best of the S&P 500’s 11 sectors, up 1.72%, while communication services was the worst, down 1.57%, as Meta’s fundraising weighed on the group. Nvidia rose 2.39%, Micron 2.98% and Broadcom 2.33%, and Tesla jumped 5.21% to $391.62, its highest in more than three months, after Barclays upgraded the stock, Reuters said. Netflix fell 2.96% and Alphabet 1.06%. The Russell 2000 rose 0.38% to 2,786.42 and the CBOE Volatility Index fell about 5% to 18.39.
Anthropic’s filing was the catalyst traders cited most. The prospectus showed revenue above $16 billion in the first half of 2026, about 14 times the level a year earlier, alongside a net loss of $80.7 billion, according to reporting on the filing, and Reuters said it helped AI-linked names including CoreWeave recover earlier losses. “Today’s all about the Anthropic release, so we’re back on a little bit of an optimistic tilt,” JP Powers of RWA Wealth Partners told Reuters. With more than a third of S&P 500 companies reporting this week, that optimism is provisional. Our markets desk tracks the sector board.
Europe and Asia
Europe had its most uniform day in weeks: the STOXX 600 gained 0.77% to 640.66, the Euro Stoxx 50 added 0.79% to 6,116.23, Germany’s DAX rose 0.91% to 25,410.84, France’s CAC 40 climbed 0.83% to 7,847.32, the FTSE 100 advanced 0.72% to 10,767.33 and Italy’s FTSE MIB led with a 1.29% gain. Germany’s Ifo business climate index improved to 90.2 in October from 89.9 in September, ahead of consensus, and banks were the strongest sector, up 1.41%, while oil and gas was the only decliner, slipping 0.19% as crude eased — a precise inversion of Friday, when energy stood alone on the upside.
Asia was mixed, and the split ran through the chip trade: Japan’s Nikkei 225 fell 0.80% to 62,189.65 and South Korea’s KOSPI dropped 1.46% to 5,469.47 as semiconductor names slid on fresh AI-spending doubts, ShareCast reported via TradingView. Hong Kong’s Hang Seng rose 0.51% to 23,211.81 and the Shanghai Composite added 0.19% to 3,697.52, with state bank shares among the gainers as China’s Communist Party opened its Fifth Plenum in Beijing, Yonhap Infomax reported. Australia’s ASX 200 rose 0.17% to 8,809.90 and India’s Nifty 50 gained 0.68%.
The day’s violent move was in São Paulo. The Ibovespa plunged about 13.7% to 176,906 after Lula won Sunday’s runoff with 51.79% of valid votes against 48.21% for Flávio Bolsonaro, a result Reuters called a shock that defied the polls; exchange operator B3 halted trading for 30 minutes under its circuit breaker, and the Wall Street Journal reported the real fell about 8% against the dollar, on pace for its largest one-day decline in records dating to 2007, while the U.S.-listed iShares MSCI Brazil ETF dropped about 20% and Petrobras’s American depositary receipts fell about 14%. Investors had spent the three weeks since Bolsonaro’s first-round lead buying Brazilian assets on expectations of tighter spending; Monday unwound that trade in hours, with local banks hit hardest — Banco do Brasil down 27.3% and Bradesco 21.2%, TradingView reported. The halt was B3’s first circuit breaker since March 2020, and the fall was the index’s worst since the pandemic onset, the Journal reported. Bolsonaro refused to concede, leaving the fiscal plan investors await still unwritten.
Rates, currencies and commodities
Treasury yields barely moved: the market is holding its breath at the 5% line. The 10-year yield ended at about 4.98% and the 30-year at about 5.30%, while the 2-year rose to about 4.71% after a $69 billion 2-year note auction met slightly softer demand, Dow Jones reported. Markets price roughly a 90% probability that the Federal Reserve holds its target range at 3.75% to 4.00% on Wednesday, according to LSEG and CME data cited in close reports; the argument is over what the Fed signals about December. For borrowers and homebuyers the level matters more than the meeting: with the 10-year pinned near 5%, mortgage relief stalls, a transmission our explainer on how mortgage rates are actually set walks through step by step. The dollar firmed in Market Briefer’s delayed data, with the Dollar Index at 102.01, EUR/USD at 1.1179, GBP/USD at 1.3343 and USD/JPY at 157.44.
No verified investment-grade or high-yield spread print from FRED or a market-close report was available at publication time, so no spread figure is reported here. The day’s credit story ran through equity and structured financing instead: Meta’s planned $95 billion equity raise, and SpaceX’s arrangement for an Apollo Global Management affiliate to buy AI chips and server hardware and lease them to the company, with principal payments of about $40 billion, Reuters reported — a capital race shifting toward equity and asset-backed structures while benchmark borrowing costs sit near 5%.
Oil retreated as diplomacy moved. Brent crude fell 5.53% to $110.27 a barrel in Market Briefer’s delayed data and WTI fell 1.96% to $101.25, after Reuters reported Brent near $114.82 in European trading on hopes of easing U.S.–Iran hostilities: Qatari mediators travelled to Tehran on Sunday, and senior Saudi, Turkish and Pakistani officials were set to meet Iranian leaders there on Monday, even as the Houthis claimed more attacks on Saudi energy sites. Friday’s $116.72 Brent settlement, published in our previous edition, was the near-six-month high from which Monday’s premium leaked out. Gold rose to $4,031 an ounce in the delayed data, copper added 1.06% to $6.54, and natural gas was the board’s outlier, up 15.11% to $3.04. The full board is on the commodities desk. In crypto, Bitcoin eased 0.42% to $80,013 and Ethereum fell 1.06% to $2,312 in Market Briefer’s CoinGecko-sourced data.
What Would Change This Read: This interpretation would weaken if Microsoft and Alphabet report on Wednesday with AI revenue growth clearly outrunning their capital spending while the 10-year yield holds below 5%, suggesting last week’s AI problem was valuation jitters, not financing costs. In particular, watch Meta’s shares as its $35 billion first tranche is marketed, because it would distinguish between the current interpretation — that at 5% yields the build-out must increasingly be equity-funded and dilutive — and the alternative that investors will fund AI expansion on almost any terms.
What to watch tomorrow: Tuesday, October 27 brings U.S. durable goods orders for September, the Case-Shiller home price index, September new home sales and October consumer confidence, alongside a $70 billion 5-year note auction, as the Federal Open Market Committee opens its two-day meeting. The week’s centre of gravity stays Wednesday’s Fed decision at 2:00 p.m. ET and the Microsoft and Alphabet reports after the close, followed Thursday by the first estimate of third-quarter GDP, the September PCE price index, the European Central Bank decision and Amazon’s earnings, with the Bank of Japan closing the central-bank sequence on Friday.
This is not investment advice. The Global Close is AI-assisted market research produced with automated data checks; figures are verified against market-close reports and the site’s delayed data feeds at publication time.