Corporate America: November 19, 2026 — Anthropic’s Record Debut Could Not Stop a 2% Sell-Off
Anthropic opened at $111.50 and closed at $97.17 in the largest IPO on record, but the S&P 500 fell 2.02% for a sixth straight loss as Walmart, Williams-Sonoma, Intuit, Ross and Gap guidance tested the consumer and AMD slid on a short-seller report.
5 min read
Corporate America got the largest stock-market debut in history on Thursday and sold off anyway. The S&P 500 fell 147.80 points, or 2.02%, to 7,175.83, its sixth straight decline and its longest losing streak since April 2024, while the Dow Jones Industrial Average dropped 1,101.11 points, or 2.19%, to 49,097.06, its first close below 50,000 since June, and the Nasdaq Composite fell 550.69 points, or 2.25%, to 23,879.20. All 11 of the S&P 500’s sectors fell, with communications services and consumer discretionary shares down about 3% and technology, industrials, materials and healthcare down about 2%, according to Reuters, in a session tracked throughout the day on our Corporate America desk.
Anthropic supplied the morning’s euphoria and its fade. The Claude developer’s shares opened at $111.50, up 34% from the $83 initial public offering price, touched $115.10 and briefly carried a valuation above $2 trillion, then slid to close at $97.17, up 17.1% on the day, according to Finnhub closing data. The offering itself was the largest on record: 980 million shares sold at $83 raised about $81 billion and valued the company at about $1.5 trillion at pricing, Reuters reported. The longer-term arithmetic is the market’s problem. Reuters put Anthropic’s compute commitments at around $900 billion, perhaps closer to $1 trillion, against annualized revenue of just over $80 billion last month — a gap that helps explain why a record debut could not hold the close.
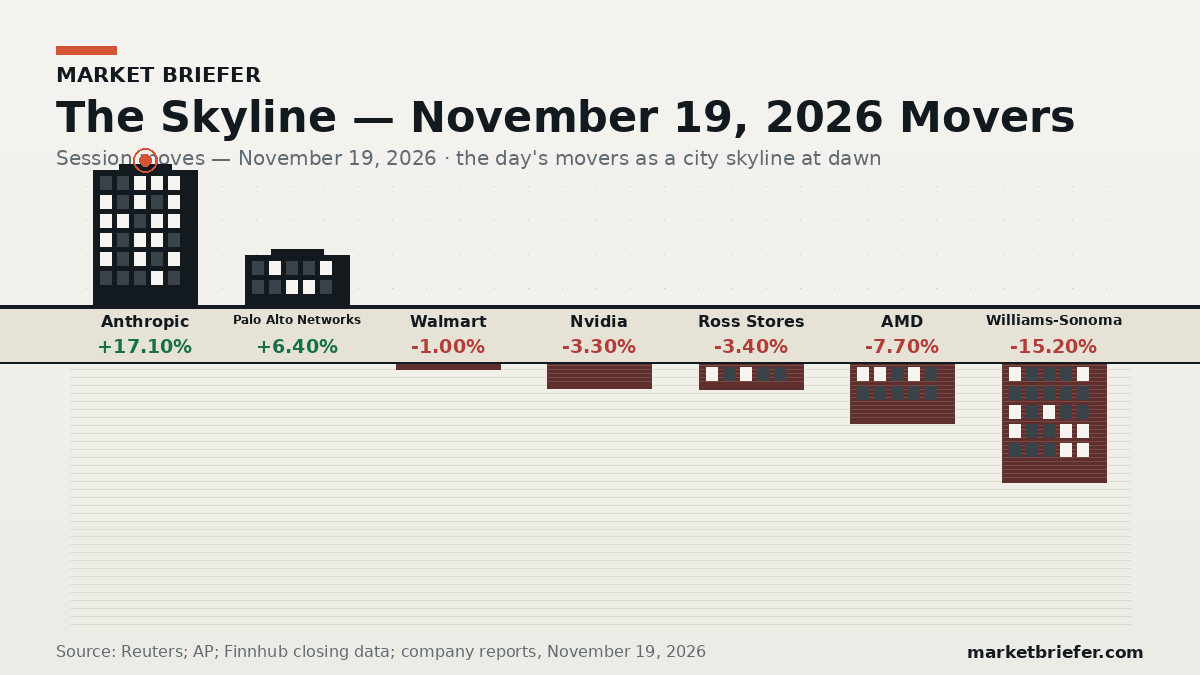
Walmart, the day’s other bellwether, beat modestly and warned plainly. Total revenue rose 5.2% to $188.84 billion, better than expected, adjusted earnings reached $0.65 a share and edged past estimates, U.S. comparable sales excluding fuel rose 2.9%, in line with estimates, and U.S. e-commerce sales rose 23%, Reuters reported. The company raised its fiscal 2027 net sales growth forecast to 4.9% to 5.2%, from 4% to 5%, and its adjusted earnings forecast to $2.84 to $2.89 a share, from $2.80 to $2.87 — both still below the 5.5% sales growth and $2.88 a share analysts had expected. Chief Executive John Furner warned that surging diesel and transportation costs were working their way into the cost of goods. Shares closed down 1.0% to $126.04. Williams-Sonoma showed what happened when a retailer merely matched the bar, the pattern our Earnings Season Playbook warns about. Revenue rose 5.8% to $1.99 billion, just below the $2.00 billion expected, adjusted earnings of $2.19 a share matched consensus, and the company reiterated rather than raised its full-year guidance while flagging fourth-quarter freight costs. The stock fell 15.2%, the S&P 500’s worst performance of the day.
After the Bell, Guidance Did the Damage
Intuit beat its quarter and cut its year. First-quarter revenue rose 12% to $4.35 billion, above the $4.31 billion expected, and adjusted earnings of $2.91 a share beat the $2.70 expected, but the company cut its fiscal 2027 revenue outlook to $23.08 billion to $23.37 billion, from $23.28 billion to $23.51 billion, with the reduction coming from Credit Karma. Intuit also agreed to sell Mailchimp, its email-marketing business, for $3.68 billion, and its shares fell sharply in after-hours trading. Ross Stores raised its full-year earnings outlook to $8.75 to $8.84 a share after third-quarter earnings of $1.91 a share beat the $1.87 expected on sales up 11.7% to $6.26 billion and comparable sales up 8%, yet its fourth-quarter earnings guide of $2.16 to $2.25 a share sat below the $2.27 consensus. Ross had already closed down 3.4% to $219.88 in the regular session and slid further after the bell. Gap completed the mixed retail picture: net sales rose 2% to $4.01 billion, adjusted earnings of $0.82 a share beat the $0.78 expected, and the company cut its full-year sales outlook to roughly flat, from growth of 1% to 1.5%, and its adjusted earnings outlook to $2.29 to $2.34 a share, from $2.35 to $2.45, with holiday-quarter sales expected flat to down 1% against expectations for a 2.6% increase, Reuters reported. Gap shares rose more than 2% in extended trading, helped by better Old Navy sales and the naming of Vuori executive Ashley Kechter to lead Athleta.
Chips, Jobs and a Very Large Game
The chip trade took a separate hit. Advanced Micro Devices fell 7.7% to $489.19 after Hunterbrook disclosed a short position and its media arm alleged that newer AMD firmware kept appearing in server updates from IEIT Systems, a Chinese server maker placed on the U.S. Entity List in March 2025. Hunterbrook itself said its findings do not establish a violation of export controls, and AMD said the claims misrepresent its practices. Nvidia fell 3.3% and is now down 40% from its peak last month, according to Reuters. Palo Alto Networks was the rare riser, closing up 6.4% to $361.73 as investors continued to reward Wednesday evening’s earnings beat and raised guidance. On the jobs and footprint front, Qualcomm is eliminating about 520 positions across its California offices, including about 442 in San Diego, according to Worker Adjustment and Retraining Notification filings, with employment ending on January 12; a separate filing disclosed a $4 billion bond offering, with about $2 billion to repay debt maturing in May 2027 and the rest for general corporate purposes. Disney’s finance chief Hugh Johnston told CNBC to expect more layoffs as Disney targets about $3 billion a year in savings by fiscal 2029. The morning’s labor data pointed the same way as the tape: initial jobless claims rose to 203,000, above the 198,000 expected, continuing claims jumped 70,000 to 1.763 million, and the Philadelphia Fed’s manufacturing index fell to 6.3 from 20.9 in October, its lowest since May. Take-Two Interactive, meanwhile, launched Grand Theft Auto VI on Thursday at $79.99, more than 13 years after the previous edition, with a Metacritic score of 99 and Sensor Tower estimating about 17 million copies sold before launch.
The one to watch is Friday, November 20. BJ’s Wholesale Club reports before the open, with the earnings calendar putting expectations at $1.29 a share on about $6.14 billion of revenue, alongside Moog, IES Holdings, Frontline and the Buckle, and the regular session will give the first verdict on the after-hours falls in Intuit and Ross Stores and the rise in Gap. The University of Michigan’s final November consumer sentiment reading lands in the morning, and Federal Reserve Governors Christopher Waller and Lisa Cook are scheduled to speak, three weeks before the December meeting the market now expects to bring another increase.
This is not investment advice. Corporate America is AI-assisted research produced with automated data checks; figures are verified against the cited sources at publication time.
See Market Briefer first in Google
Add to Preferred Sources